Buying Waterfront Property in Beaufort: What You Need to Know
BuyingWaterfrontBeaufort
Waterfront property in Beaufort is not one thing. It's a dock on the Beaufort River. It's a tidal creek view with marsh between you and the water. It's a private pond in a planned community. It's a home on Port Royal Sound with views all the way to the ICW.
These are very different purchases with very different due diligence requirements, very different insurance costs, and very different long-term values. If you're buying waterfront in the Lowcountry, you need to understand which type you're actually buying — before the offer goes in.
What "Waterfront" Actually Means in Beaufort
The term gets used loosely. Here's a working breakdown of what you'll encounter:
Navigable waterfront — direct access to a body of water. Depth is measured at the dock, not by the water body's name. These properties have the most complex permitting. A dock here is a serious asset.
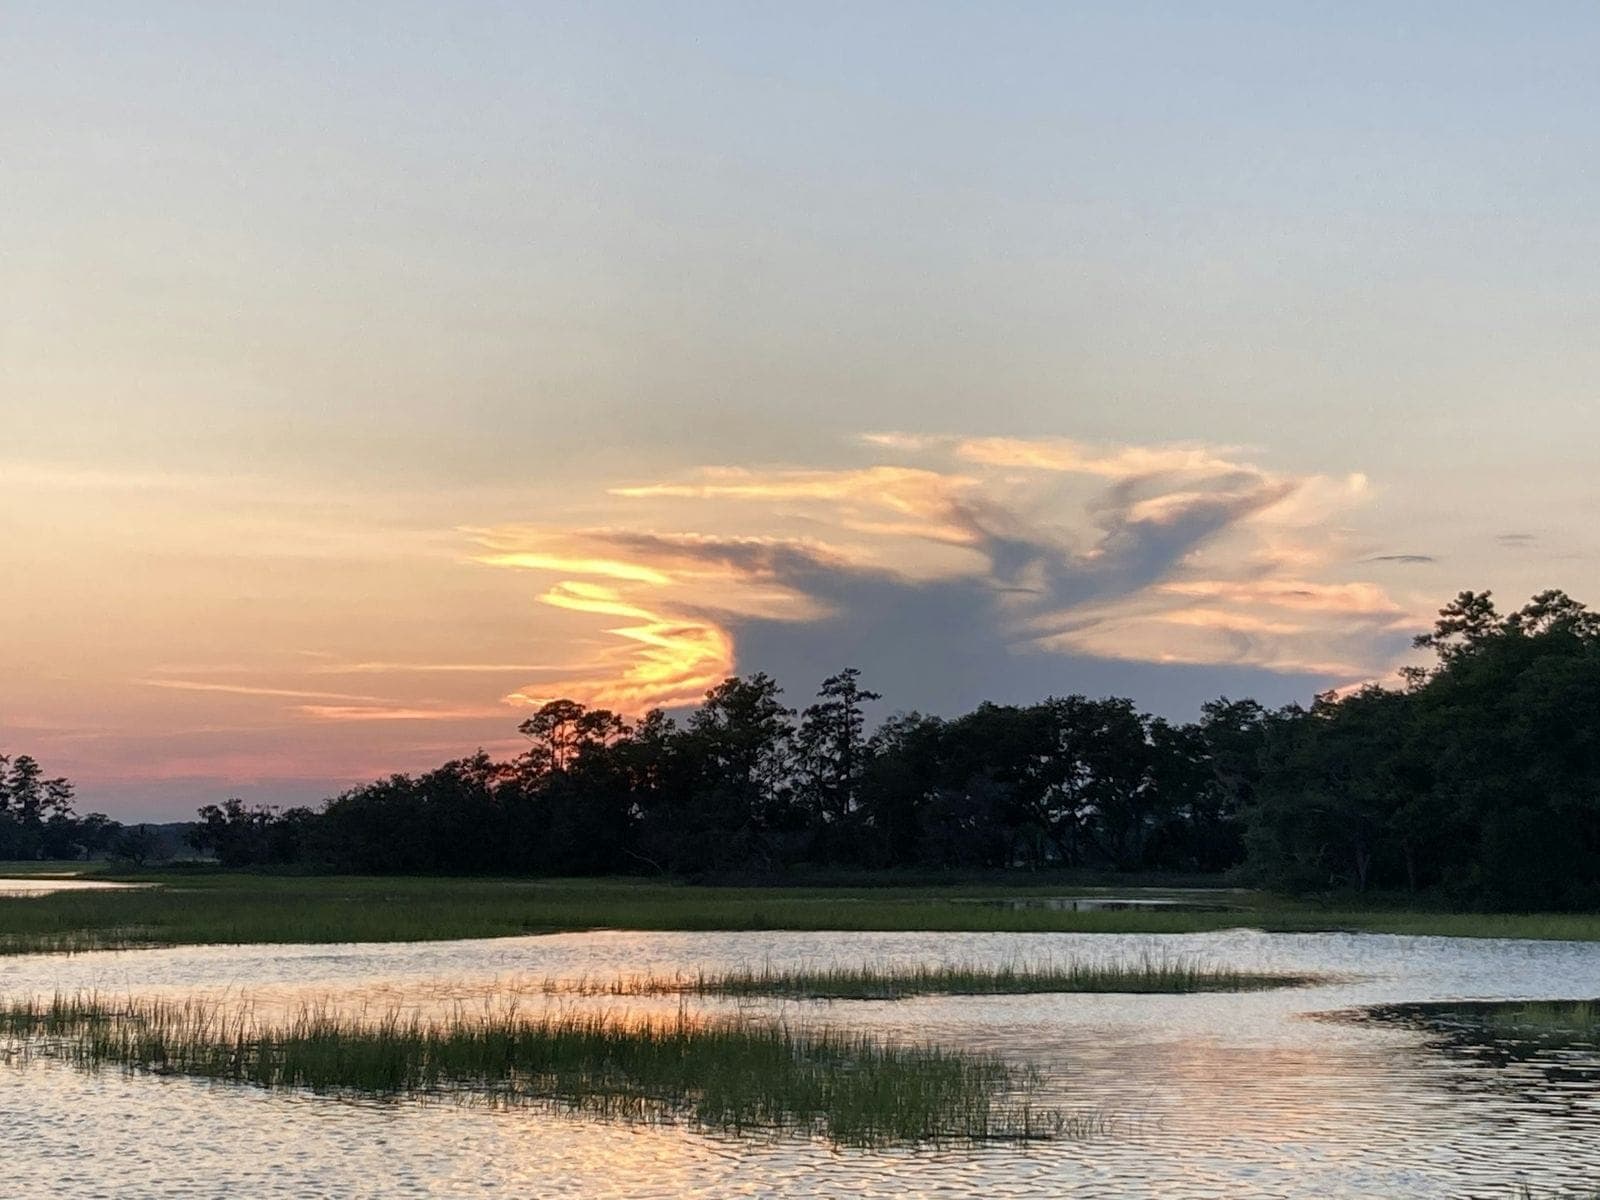
Tidal creek / marsh-front — the most common "waterfront" in Beaufort. You have water views and often a dock, but the water is shallow and tidal. At low tide, you're looking at mud. Still beautiful, still valuable — but you can't always dock a boat with a deep draft, and your dock permit process involves both state and federal review.
Pond/lagoon front — common in planned communities like Habersham and others. A pond view is nice and adds value, but it's not the same as river access. Make sure the listing is clear about what you're actually getting.
The listing description will often use "waterfront" for all of these. It's your job — and your agent's — to understand what the water actually is before you fall in love with the view.
Most Beaufort 'waterfront' is tidal marsh-front — beautiful, but shallow at low tide.
Flood Zones: The First Question to Ask
Before anything else, pull the FEMA flood map for any waterfront property you're considering. In Beaufort County, a significant number of waterfront and near-waterfront properties sit in Zone AE — the high-risk flood zone requiring federally backed flood insurance for any mortgage.
What this means practically:
Flood insurance is mandatory if you have a mortgage and the property is in Zone AE or higher. This isn't optional and the lender will require it.
The cost is per building. An elevation certificate is what a flood quote uses. Do not budget from a neighbor's bill or from a dollar range in a blog. The walkthrough is the flood guide.
FEMA's NFIP (National Flood Insurance Program) is the primary insurer, with private market options available for some properties. Shop both.
A pre-FIRM discount, if the seller has one, does not automatically mean a higher rate. Under Risk Rating 2.0 the zone is no longer the rating element, and a discount can transfer with rules. Read that section in the flood guide before you assume an older house costs more to insure.
Ask for the elevation certificate early. If the seller doesn't have one, a licensed surveyor can produce it. Get the price from the surveyor before you treat it as a small line item.
Dock Permits: Know Before You Build
A dock is one of the most valuable features on a Beaufort waterfront property — and also one of the most regulated.
In South Carolina, any dock or pier over navigable waters requires permits from:
SC Department of Environmental Services, Bureau of Coastal Management — the permit office for docks in tidal and navigable waters. This was DHEC's Ocean and Coastal Resource Management program. Start at the Bureau of Coastal Management.
Army Corps of Engineers — for docks over navigable waters
Potentially local zoning review as well
Key things to understand:
Permits are tied to the property, not the owner. An existing, permitted dock transfers with the property. Confirm the dock has valid coastal permits before closing. An unpermitted structure is a liability you'll inherit.
New dock permits can take time and aren't guaranteed. If a property doesn't have a dock but you want one, verify with the Bureau of Coastal Management that the waterway and lot configuration qualify before making that a core part of your purchase decision.
Shared dock situations are common. Some tidal creek lots have shared community docks with deeded access rights. Understand what you own versus what you have access to. Check the HOA docs or the plat.
Maintenance is your problem. Saltwater and sun are hard on dock structures. Budget for regular maintenance and eventual replacement of pilings, decking, and hardware. This is a real cost of waterfront ownership here.
Riparian Rights: What You Actually Own
When you buy waterfront in South Carolina, you own to the mean high-water mark — not to the centerline of the river. The state owns the submerged lands below that line.
What this means in practice:
You have the right to wharf out (build a dock) to reach navigable water, subject to permits.
You don't own the water or the river bottom.
Your rights are appurtenant to the land — they don't exist independently and can't be sold separately.
Ask your closing attorney to review the deed description carefully on any waterfront purchase. Riparian rights should be referenced. If they're not, ask why.
Insurance: Budget for the Real Number
Waterfront homeownership in the Lowcountry comes with an insurance stack that inland buyers don't face:
Hazard/homeowners insurance — standard, but coastal properties sometimes face surcharges or limited carrier options.
Flood insurance — required in most AE-zone waterfront situations. Get a quote early; don't wait until you're under contract.
Wind insurance — Beaufort County is in South Carolina's coastal zone, and some carriers exclude wind or require a separate policy or endorsement. Review your policy carefully.
Quote all three before you write. The total depends on the house. This post does not publish a dollar range for the stack.
What to Inspect (Beyond the Standard Home Inspection)
A standard home inspection covers the structure. On a waterfront property, you need more:
Elevation certificate — if it's not current, get one. Your insurance quotes depend on it.
Dock inspection — have a marine contractor assess the condition of any existing dock. Look at piling condition, decking integrity, electrical (if wired), and overall life expectancy.
Bulkhead condition — if the property has a bulkhead (seawall), its condition is critical. Bulkhead replacement is expensive. A failing bulkhead can affect the property's stability.
HVAC and exterior surfaces — salt air accelerates corrosion and wear on HVAC systems, metal components, and finishes. Ask about service history and maintenance routine.
Septic vs. sewer — many older waterfront properties are on septic. Make sure the system is inspected, not just assumed to be functional.
What Waterfront Costs to Own
Waterfront homes cost more to own (insurance, maintenance, dock upkeep) and can be harder to insure after a major storm event. These costs are part of owning waterfront.
Bottom Line
Buying waterfront in Beaufort takes more due diligence than a standard purchase. The view is not a substitute for the flood map, the dock permit, or the insurance quote.
Know what "waterfront" means for the specific property. Pull the flood map. Get the elevation certificate. Verify the dock permits. Model the insurance costs before you make an offer. Work with an agent who's done this before — not one who's guessing alongside you.
We sell waterfront properties in Beaufort regularly and know the questions to ask before they become problems. If you're looking at waterfront listings or want to understand what you're actually getting on a specific property, reach out — we're glad to walk through it.